Skip to content
Fkah

Credit risk on your receivables

Know who pays, who's slipping, and where your ledger is concentrated

Lots of invoices, even more customers, and no clear picture. The engine reads your receivables invoice by invoice, gives every customer a score with a plain word, and shows you what is behind it. Then your team decides.

A subscription to software that reads your ledger. It sells no assessment of third parties.

The idea

What it does for you

Your ledger knows. Nobody has read it. Every invoice looks like the next, and you can't tell which customers have started to slip, or how much of your ledger hangs on one name. The engine reads the whole ledger, not a sample and not just the ten biggest customers.

Every customer gets a score from 0 to 100 and a word you understand at a glance: Strong, Sound, Moderate, Weak or Needs attention. Under it sit the reasons, line by line: how it pays, where its invoices sit on the aging ladder, how much of your ledger it holds, and whether its invoices are sound.

Government buyers get their own reading. Their delays follow the approval cycle, not their ability to pay. So the engine reads the delay as timing, shows the government share of your ledger on its own, and doesn't mark it down like a company that won't pay.

How

How it works

  1. 01You

    Connect your accounting system through the connectors, or drop your receivables file into the data pool

    At the start, then with every update
  2. 02The engine

    Checks every invoice: is the data complete? Is the e-invoice stamped with an intact chain? Any duplicates?

    Before any score
  3. 03The engine

    Reads every customer: payment behaviour, the aging ladder, concentration, and gives it a score with a word and reasons

    In the same cycle
  4. 04Your team

    Reads the score, its reasons and what changed, exports PDF or Excel reports, and decides

    Whenever it wants
See all the steps

From the platform

Your ledger on one screen

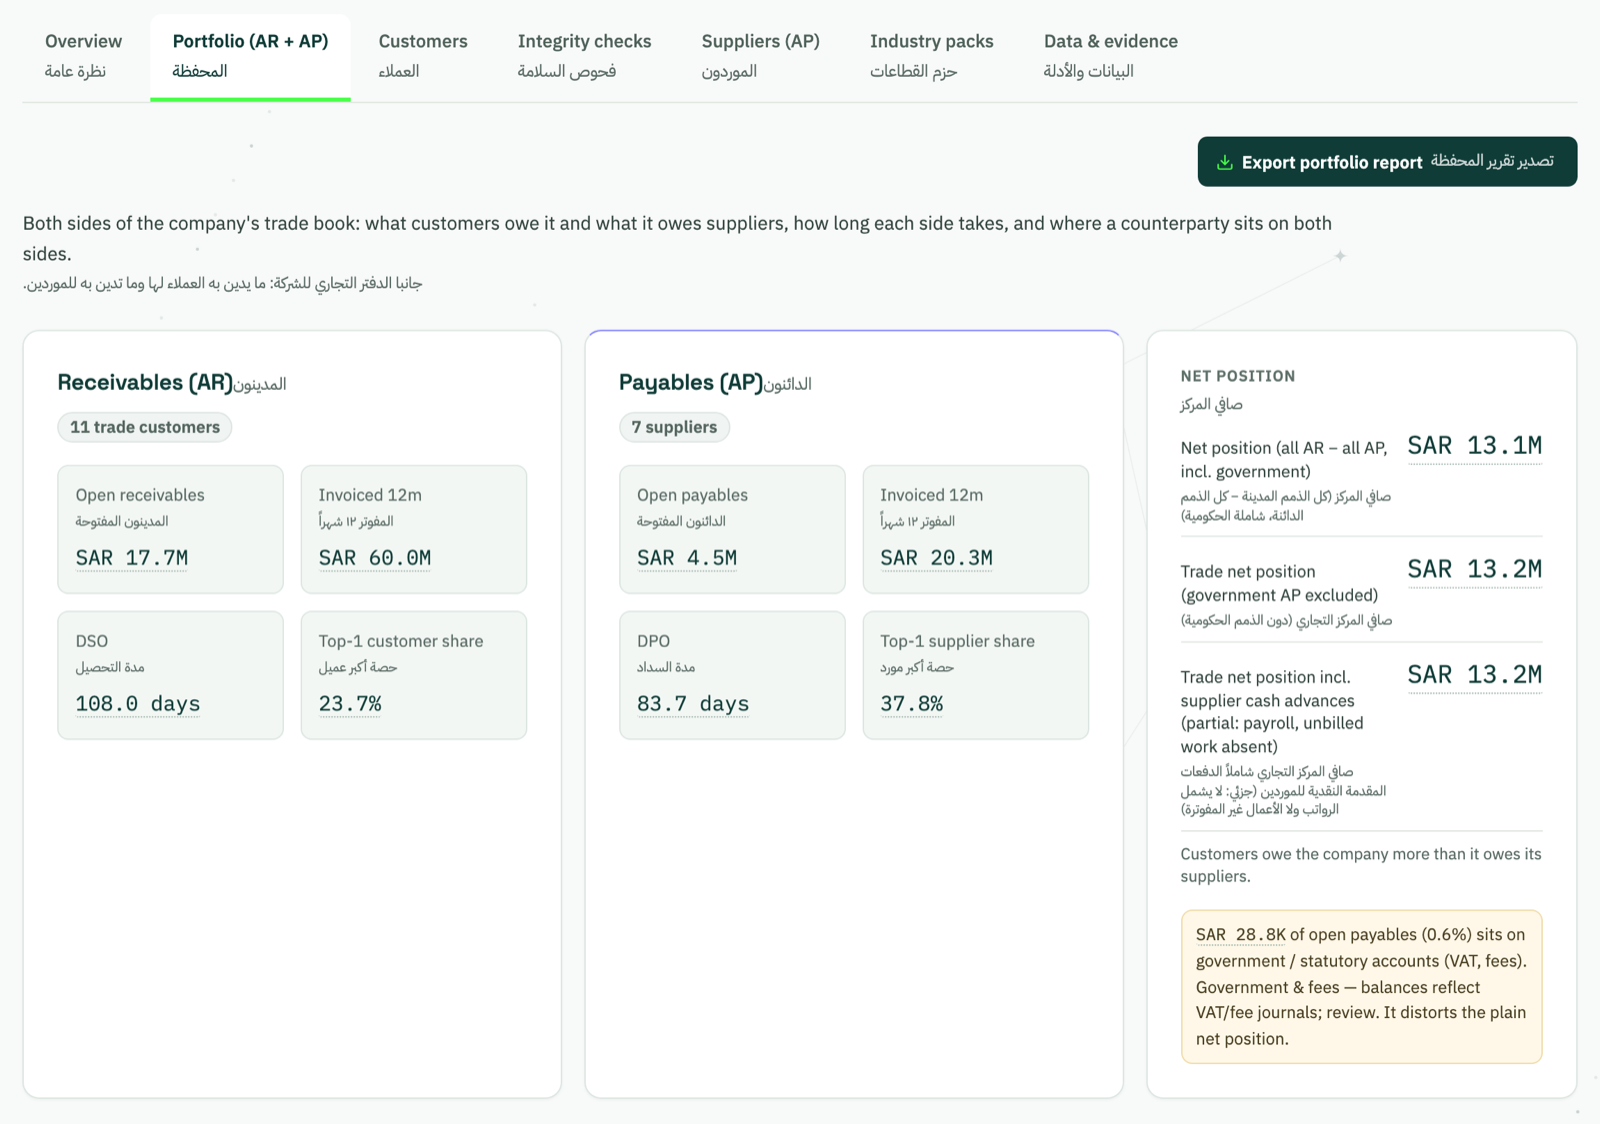
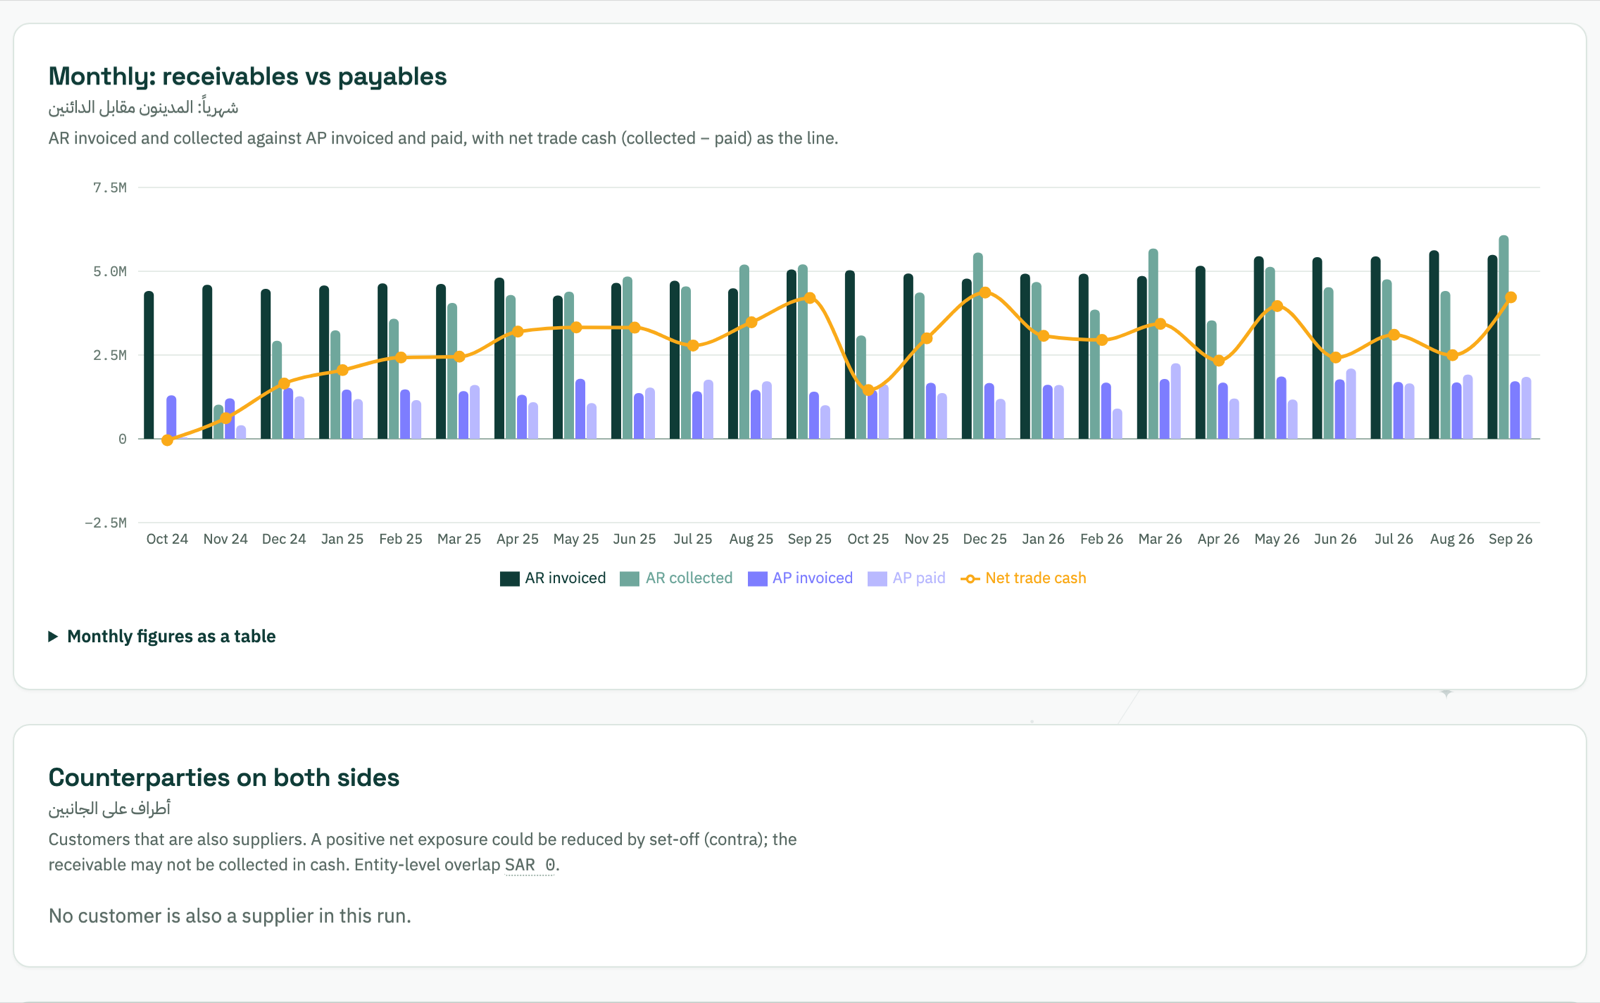
Open balances, days to collect, your biggest customer's share, and two years of collections. Captures from the platform on a sample company's data.

The Fkah portfolio screen: receivables and payables cards with the net position
Both sides of your trade book and your net position, at a glance.
The Fkah monthly chart of collections and payments over two years
Collections and payments month by month, across two years.

The engine, step by step

A motion graphic of how the engine reads financial accounts

Six steps: the invoices arrive scattered with the account statement, the engine reads and orders all of them, and out come the ECL reports and the counterparties whose position is financially sound, alongside the regulatory standing and records, ending in analysis that supports your decision.

1/6Scattered invoices

Invoices from different customers arrive apart, with no clear picture of the financial accounts.

Step 1 of 6

An illustration. The counterparty names and figures here are examples we wrote to explain the reading, not the financial accounts of Fkah or of any client.

Who reads this assessment

One engine, two questions: a company that wants to know its own risks, and a financial institution reading its own portfolio.

Companies

Know your risks: a score for every customer in your ledger, with its reasons. See where your exposure is concentrated before a late payment surprises you.

  • A score for every customer, with a word and reasons
  • The government share of your ledger, on its own
  • How much of your ledger hangs on one name
  • A history of when the reading changed, and why
Financial institutions

A financial institution subscribes to read its own portfolio, with data its clients provide with their consent. The engine gives it the analysis: verified invoices, readable payment behaviour, an explained score and concentration. The decision stays with its credit committee.

  • A reading of your own portfolio, not someone else's ledger
  • The score and its reasons, every invoice's status, payment behaviour
  • The engine decides nothing and sets no credit limit
  • No pooling of third-party data, and no assessments sold

Fit

Who it suits

  • Companies that sell on credit and issue e-invoices
  • Companies with a large share of revenue from a few customers
  • Companies supplying government buyers that want to tell timing from default
  • Financial institutions reading their portfolio before a renewal or expansion

Package

Subscription and package

This assessment is in the Receivables package, and also in the Receivables + Payables package if you want both sides together.

The subscription is set by package and tier. For details, contact the team.

Matching package

Receivables

Your customers, the receivables aging ladder, integrity checks, the book-quality index, and customer and sector reports. Connectors to your accounting system come with every tier.

See the systems you can connect
Starter, Professional, Enterprise

Questions about this assessment

How is Fkah's assessment different from a credit information report?
The Fkah engine reads your own ledger: your customers, their invoices, and how they pay you. A credit information report comes from records lenders share across the market. Two different questions, and what the engine produces stays inside your account.
How do I read the score?
The score runs from 0 to 100 and comes with a word: Strong, Sound, Moderate, Weak or Needs attention. Under it are the reasons that moved it up or down, line by line, so anyone on your team can see what is behind it.
My customer is a government body and pays late. Is that a risk?
Usually it's timing, not default. Government payment follows the approval cycle, and the engine reads it that way and shows the government share on its own, so the delay shows up in the right place.
What does the e-invoice stamp prove?
The stamp and hash chain prove the document is authentic and the seller's sequence is intact. They don't prove the invoice hasn't been presented elsewhere, and we say so plainly.
All FAQs

Next step

Tell us about your ledger

Leave your details and someone from the team will get in touch. Registering commits you to nothing.

This registers interest, not an order.

Ten digits. It helps us prepare Wathq verification later.

We send updates to this address.

05XXXXXXXX or +9665XXXXXXXX

A rough band is enough.

Security check

The other side of the ledger