Skip to content
Fkah

How it works

Your ledger knows. Nobody has read it.

Connect your system. The engine checks every invoice, reads every customer and supplier, gives each one a score with a plain word and its reasons, and shows you what changed. Then your team decides.

What you see here is a subscription to software that reads your ledger and gives you the analysis. The decision stays with you.

The idea

From your ledger to a clear picture, step by step

Lots of invoices, even more customers, and no clear picture. Every invoice in the ledger looks like the next, and you can't tell where your exposure sits. The engine reads the ledger invoice by invoice, separates what needs your attention from the rest, and shows you why.

The steps

What happens to your ledger, in order

Six steps, in the same order every time, on receivables and payables.

Illustrative figures and names, written to show how the reading works. They are not Fkah's portfolio or any client's.

  1. Step 1

    Connect your system

    You start from your ledger as it sits in your accounting system. Connectors pull the data from your system, or you drop files into the data pool, or your systems send it through the API. The engine needs nothing beyond the fields every ledger already has, and your data is read for your account alone.

    See the systems and channels
    Ways your ledger reaches the engine

    How your data arrives

    • Accounting system connectorsBeta

      Microsoft Dynamics 365, Odoo, Zoho Books, QuickBooks, Xero and SAP Business One

    • Data poolAvailable

      Upload Excel, CSV or e-invoice files, or send them by secure file drop

    • APIAvailable

      Your systems send the data directly, on Professional and above

    Fields needed

    • Counterparty and its commercial registration
    • Invoice number
    • Amount
    • Issue date
    • Due date
    • Status
  2. Step 2

    Every invoice is checked

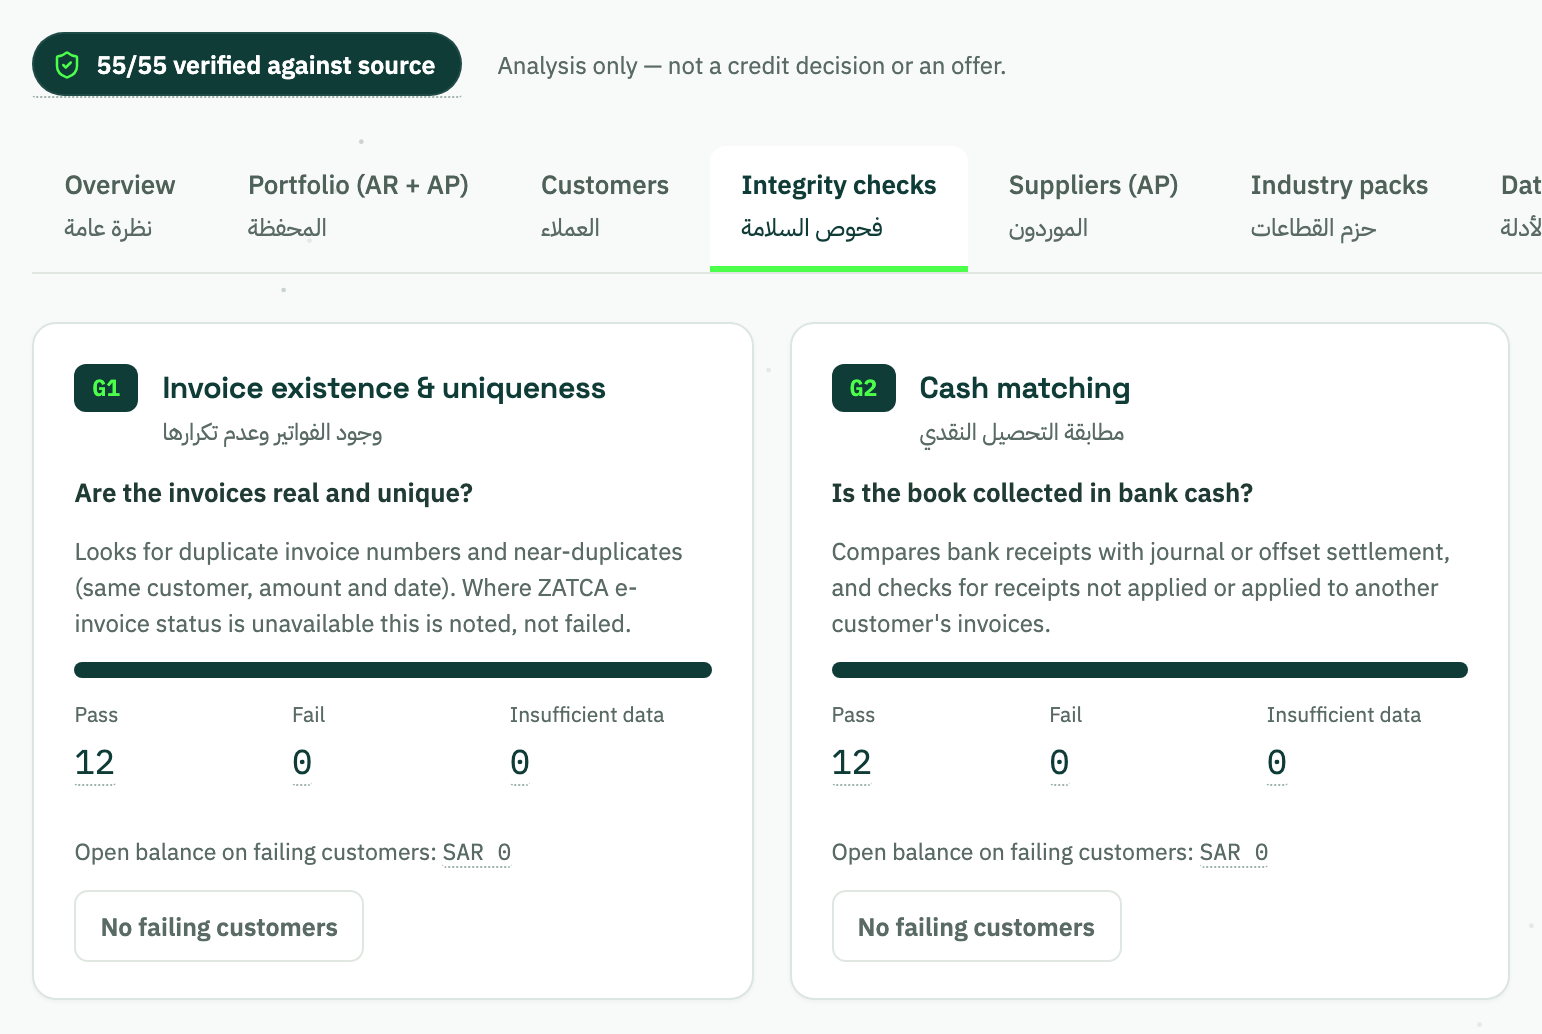
    Before any score, every invoice goes through checks: is the data complete and consistent? Does the e-invoice XML carry a valid ZATCA stamp with an intact hash chain? Is there a duplicate in the same ledger? An invoice that fails is not deleted. It is flagged, and the flag shows in its counterparty's reading.

    The Fkah data integrity screen: each figure against its source
    Every figure checked against the source.
  3. Step 3

    Every customer and supplier is read

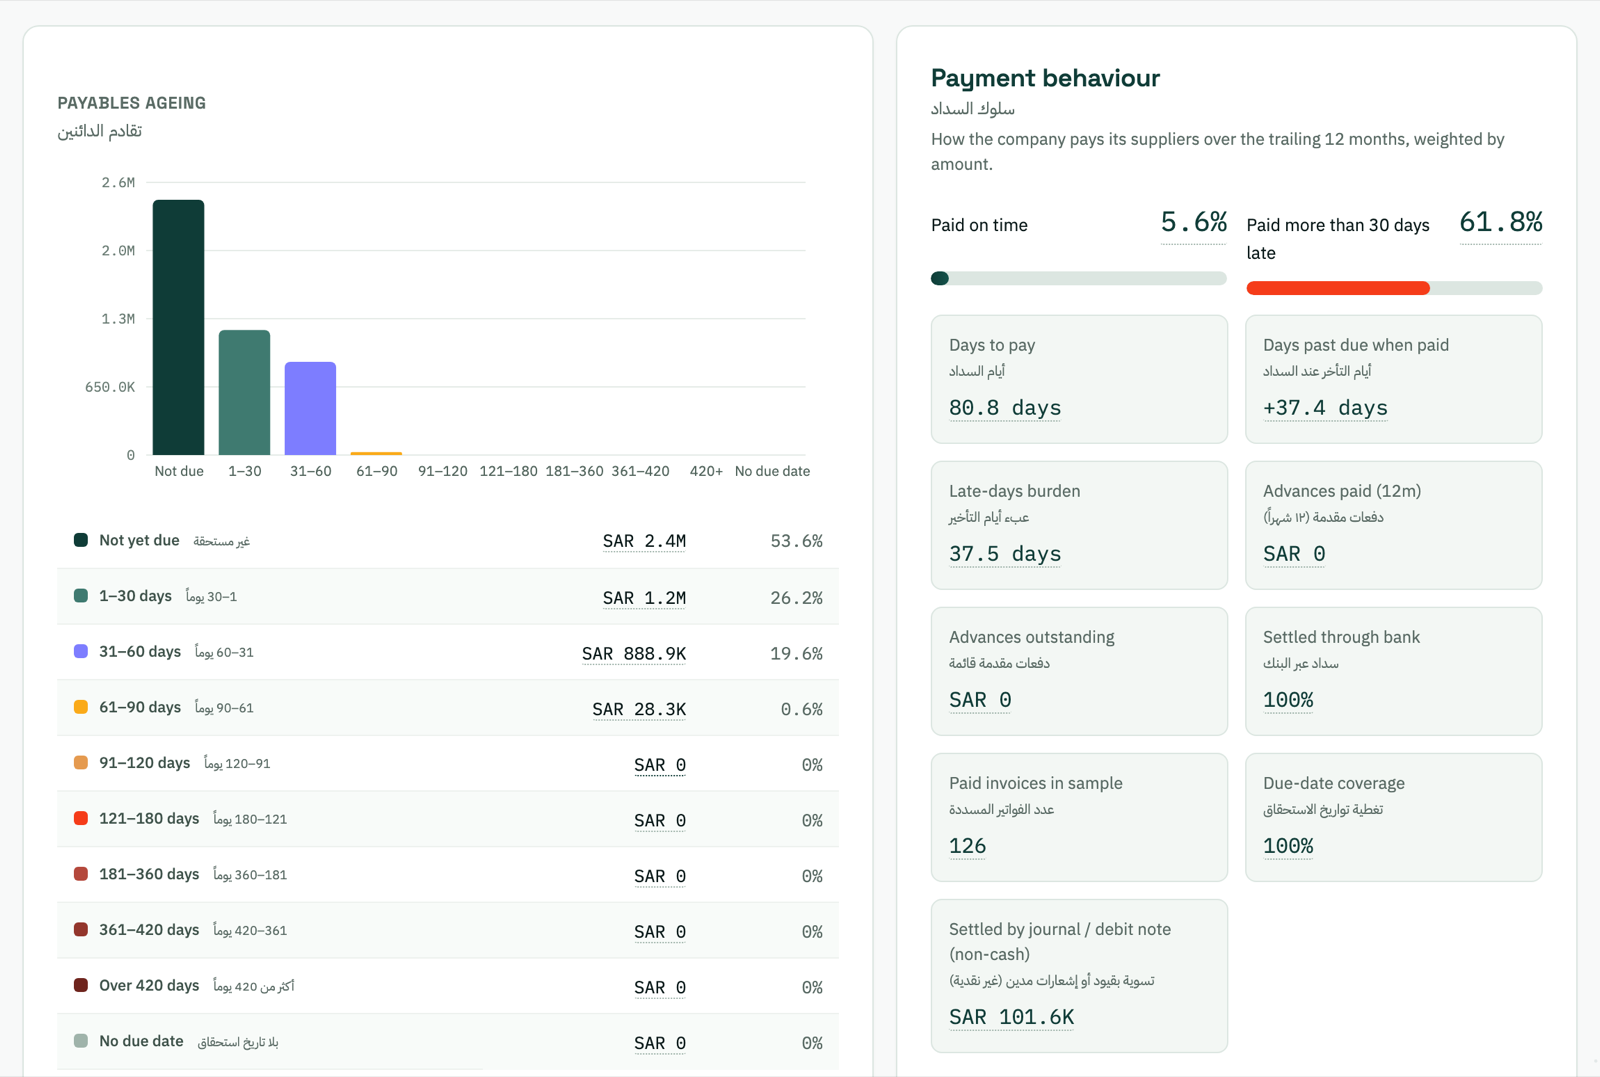
    The engine reads each counterparty on its own: how it pays, where its invoices sit on the aging ladder from not yet due to over 420 days, and how much of your ledger it holds. Government buyers get their own reading: their delays are read as timing tied to the approval cycle, not as default.

    The Fkah payables aging and payment behaviour screen
    Payables aging and payment behaviour on one screen.
  4. Step 4

    A score from 0 to 100, with a word and reasons

    Each counterparty gets a score from 0 to 100 and a word you understand at a glance: Strong, Sound, Moderate, Weak or Needs attention. Under it sit the reasons that moved it up or down, line by line, so you know what is behind it.

    An illustrative counterparty's score, with its word and reasons

    Illustrative customer: a wholesale trader

    Sound

    Score from 0 to 100

    1. Needs attention
    2. Weak
    3. Moderate
    4. Sound
    5. Strong
    0100

    Reasons

    • Pays on time on most of its invoices
    • Its invoices are stamped, with no duplicates
    • It holds a large share of your ledger

    An illustration. On the platform you see the number with its word, and every reason with its effect.

  5. Step 5

    What changed, and the reports

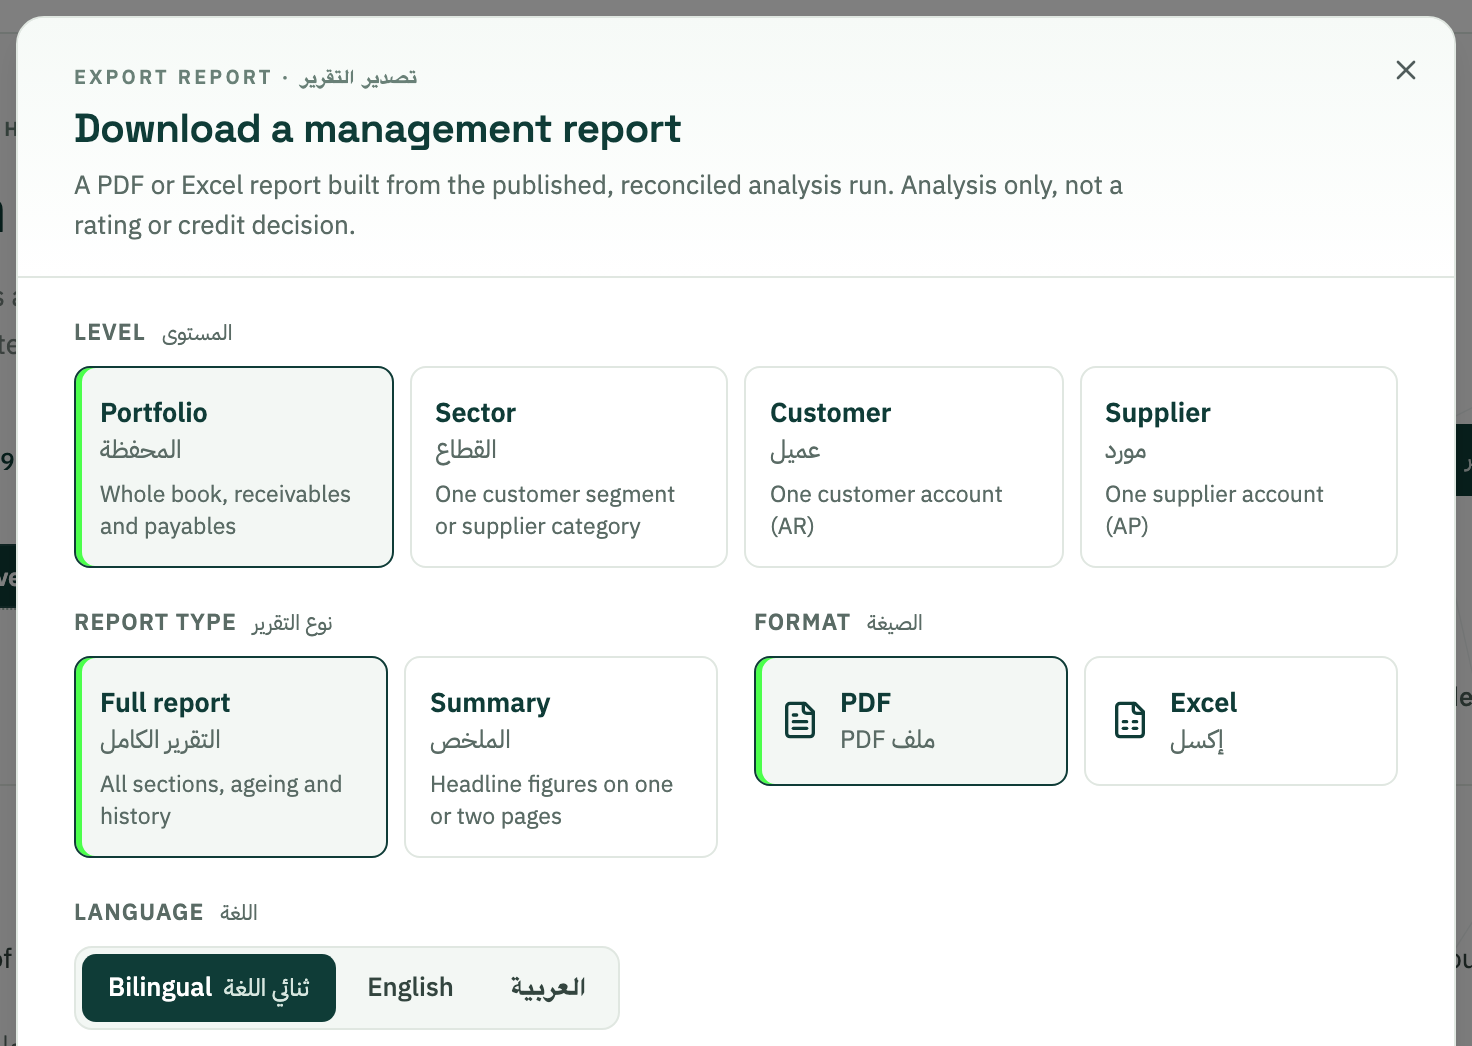
    Your ledger moves, and the reading moves with it. With every update the engine records what changed and why: a delay getting longer, concentration building on one name, an invoice with no stamp. Reports come out in Arabic and English, as PDF and Excel, ready to share with your team.

    The Fkah report export dialog: scope, content, format and language
    Export PDF or Excel reports for the whole book, a sector, a customer or a supplier, in Arabic, English or both.
  6. Step 6

    Analysis for you. The decision is your team's.

    The engine gives you the score and its reasons, the status of every invoice, payment behaviour and concentration. It sets no credit limit, no percentage, and never says approve or decline. Your team decides, on its own authority.

    What the engine gives you, and what stays with your team

    The engine gives you

    • The score, its word and its reasons
    • Every invoice's status after the checks
    • Payment behaviour and the aging ladder
    • Concentration, and what changed

    What it doesn't do

    • No credit limit
    • No percentage
    • No approve or decline
    • No decision on your behalf

    Analysis for you. The decision is your team's.

From the platform

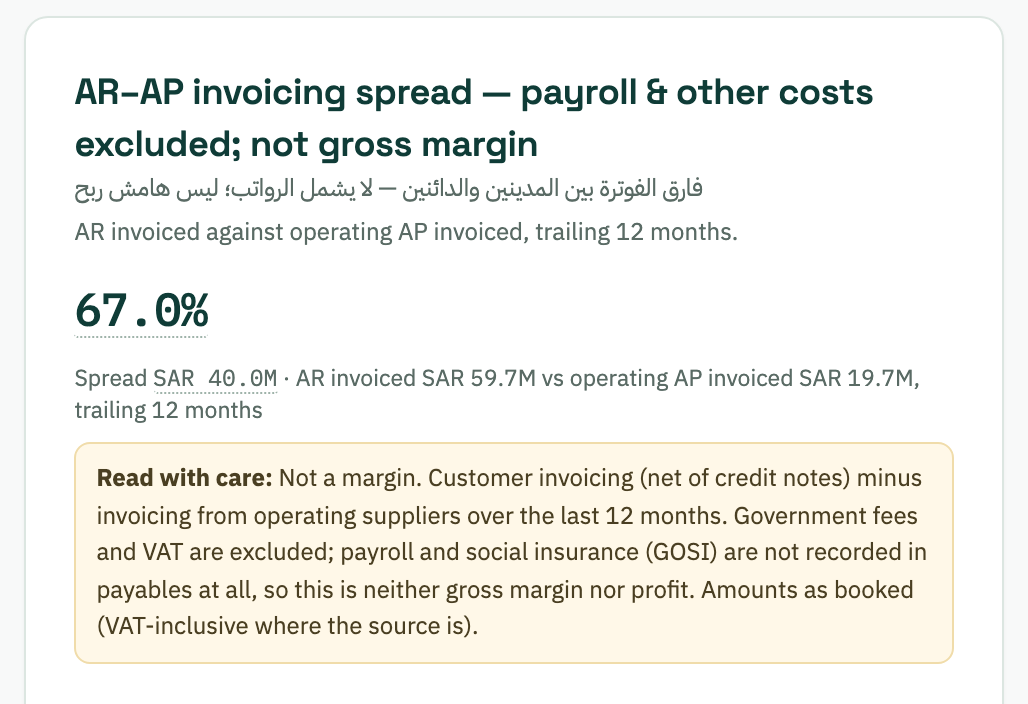
The spread between both sides

How much you invoice your customers against how much your suppliers invoice you, with the limits of the reading written beside it. This screen comes with the Receivables + Payables package.

See the packages
The Fkah AR–AP invoicing spread screen, with its caveats
The AR–AP invoicing spread, stated plainly with its caveats.

Before you start

Things worth knowing about the reading

These aren't gaps. They are product decisions, and they are what make the reading something you can trust.

  • 01

    A late government buyer isn't a default

    Government payment follows an approval cycle that takes time. So the engine reads the delay as timing, shows the government share on its own, and doesn't mark it down like a company that won't pay.

  • 02

    The stamp proves the document, nothing more

    The stamp and hash chain prove the document is authentic and the seller's sequence is intact. They don't prove the invoice hasn't been presented elsewhere, and we say so plainly.

  • 03

    No live link to ZATCA

    The engine doesn't connect to ZATCA. It reads the e-invoice files you upload and checks their stamp on our side.

  • 04

    Not a credit bureau

    The engine reads your own ledger, plus the official sources you choose in package four. It doesn't collect payment behaviour on third parties and sells no assessment of anyone. The compare page explains how it differs from a credit information report.

  • 05

    A reading, not a forecast

    The engine reads, measures and alerts you. It can't prevent a delay or know for certain who will default. What it does is show you what is happening in your ledger before it surprises you.

  • 06

    Your data is yours

    Your ledger is read for your account alone. It is never merged with other clients' data, never used to score another company, and no AI model reads your files.

Let's read your ledger

The next step is a short call to look at your ledger and your system, and pick the package that fits you.